
Commercial auto insurance for contractors in South Texas
Tools in the truck, employees behind the wheel, and the certificate of insurance every general contractor asks for before you get on the site.
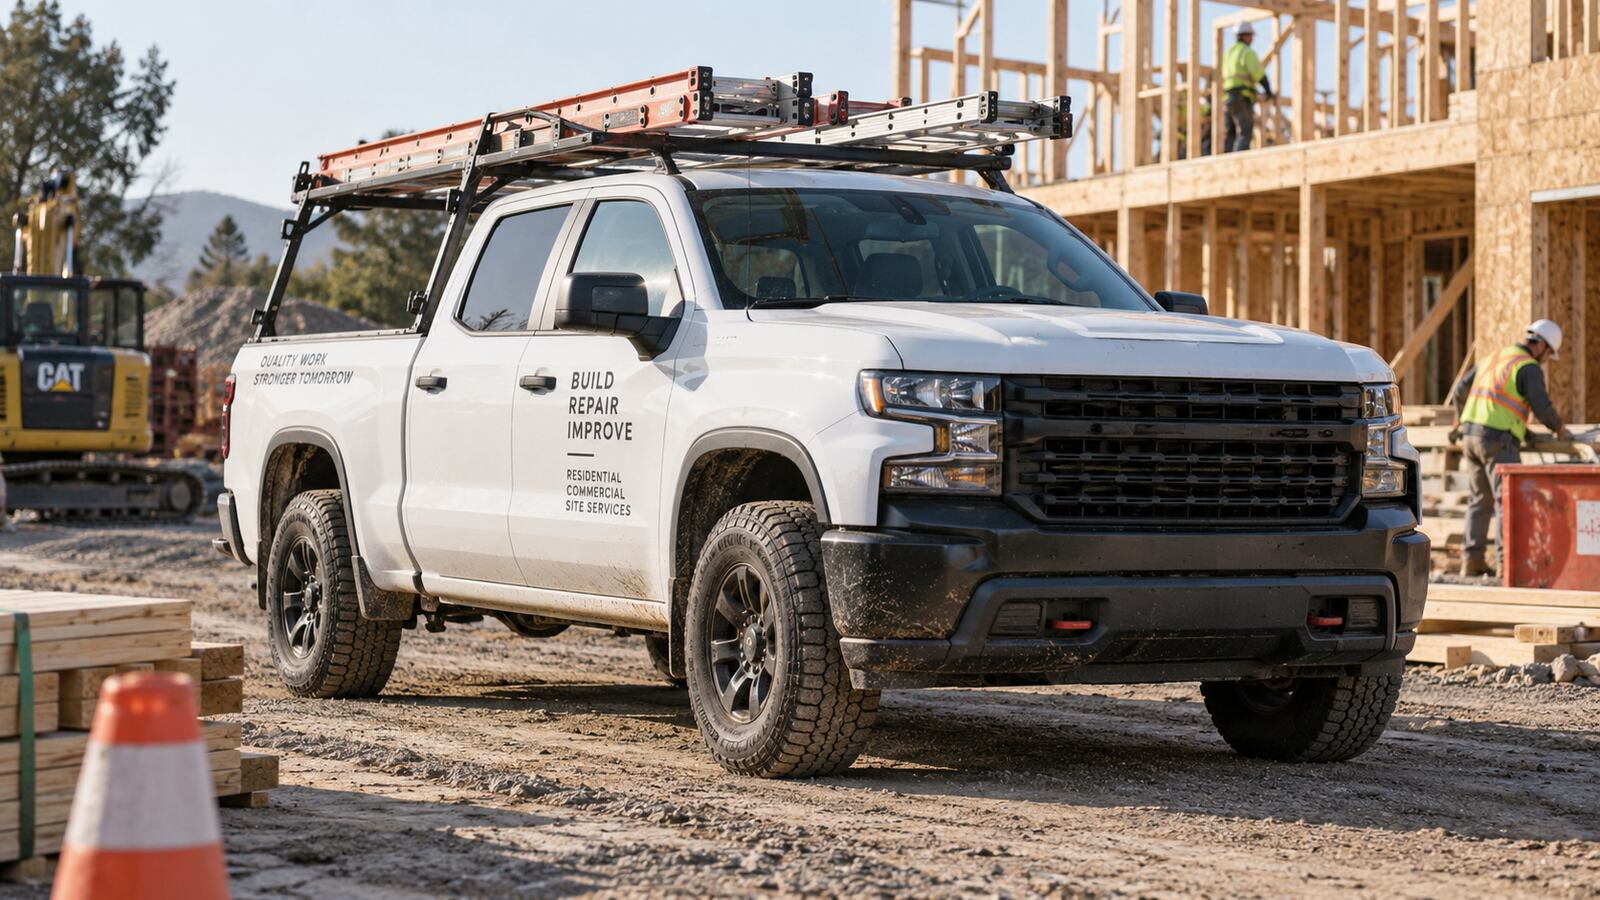
- If the truck is titled to the business or driven by employees, it needs a commercial policy. A sole proprietor driving their own truck alone may not, but tell your carrier what you do.
- The auto policy covers damage to the truck, not what is inside it. If 6,000 dollars of tools are stolen from the truck, that is a separate policy.
- Send the contract language to your agent before you sign. Some requirements cost money to meet, and it is better to know during the bid.
For most contractors the truck is the business. It carries the crew, the tools and the materials, and it is what puts you in front of a customer. It also produces most of your liability exposure, the risk of being held responsible for hurting someone or damaging their property. If you are not sure the truck belongs on a commercial policy at all, start with whether you need commercial auto insurance.
What a contractor's policy usually needs
- Liability limits high enough for the contracts you sign. One million dollars combined single limit is common. That is one number for injury and property damage together
- Coverage for employees driving, not just the owner
- Hired and non owned auto, for rented trucks and crew members' own vehicles
- Physical damage on the trucks and trailers you own, which pays to repair or replace them
- Additional insured and waiver of subrogation endorsements. These are two add ons that general contractors ask for by name
Tools and equipment are not covered by auto insurance
This surprises people every week. If your truck is broken into and 6,000 dollars of tools are taken, the auto policy covers damage to the truck, not what was inside. Tools are covered by an inland marine or contractors equipment policy. That is a separate policy for gear that moves from job to job. It is inexpensive, and it is worth listing the expensive pieces one by one.
Trailers
Trailers you own should be listed on the policy with their own values. Liability generally follows the truck doing the towing. Coverage for damage to the trailer itself does not come along automatically. If you borrow or rent trailers, ask about trailer interchange coverage.
Certificates and the paperwork loop
General contractors will not let you on the site without a certificate naming them as additional insured. That means your coverage extends to them for claims that come out of your work. Get the contract language to your agent before you sign. Some requirements cost money to meet, and it is better to know that during the bid.
Who is driving
Carriers price contractor policies heavily on driver records. One employee with a suspended license or a recent DWI can move the price of the whole policy, or get it declined. Pull motor vehicle records before you hire drivers, and again every year. That is the state's report of a person's driving history. See how to build a driver file underwriters respect.
Personal trucks used for work
A sole owner with a personal truck may be fine on a personal policy today, and not fine the day a helper drives it. This is where claims get denied.
We work with trades
Bring your vehicle list, your driver list and the certificate requirements from your general contractor. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Do I need commercial auto for one pickup?
If it is titled to the business or driven by employees, yes. A sole proprietor driving their own truck alone may not, but tell your carrier what you do.
Will my general liability policy cover a truck accident?
No. General liability excludes auto claims. The two policies are built to work together, and neither replaces the other.
What limits do general contractors usually require?
One million dollars combined single limit is the common requirement, sometimes with an umbrella above it. An umbrella is an extra layer of liability that sits on top of the auto policy. Read the contract, because the number varies.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.