
Certificates of insurance: what customers are really asking for
Additional insured, waiver of subrogation, and primary and noncontributory, translated into what each one costs you.
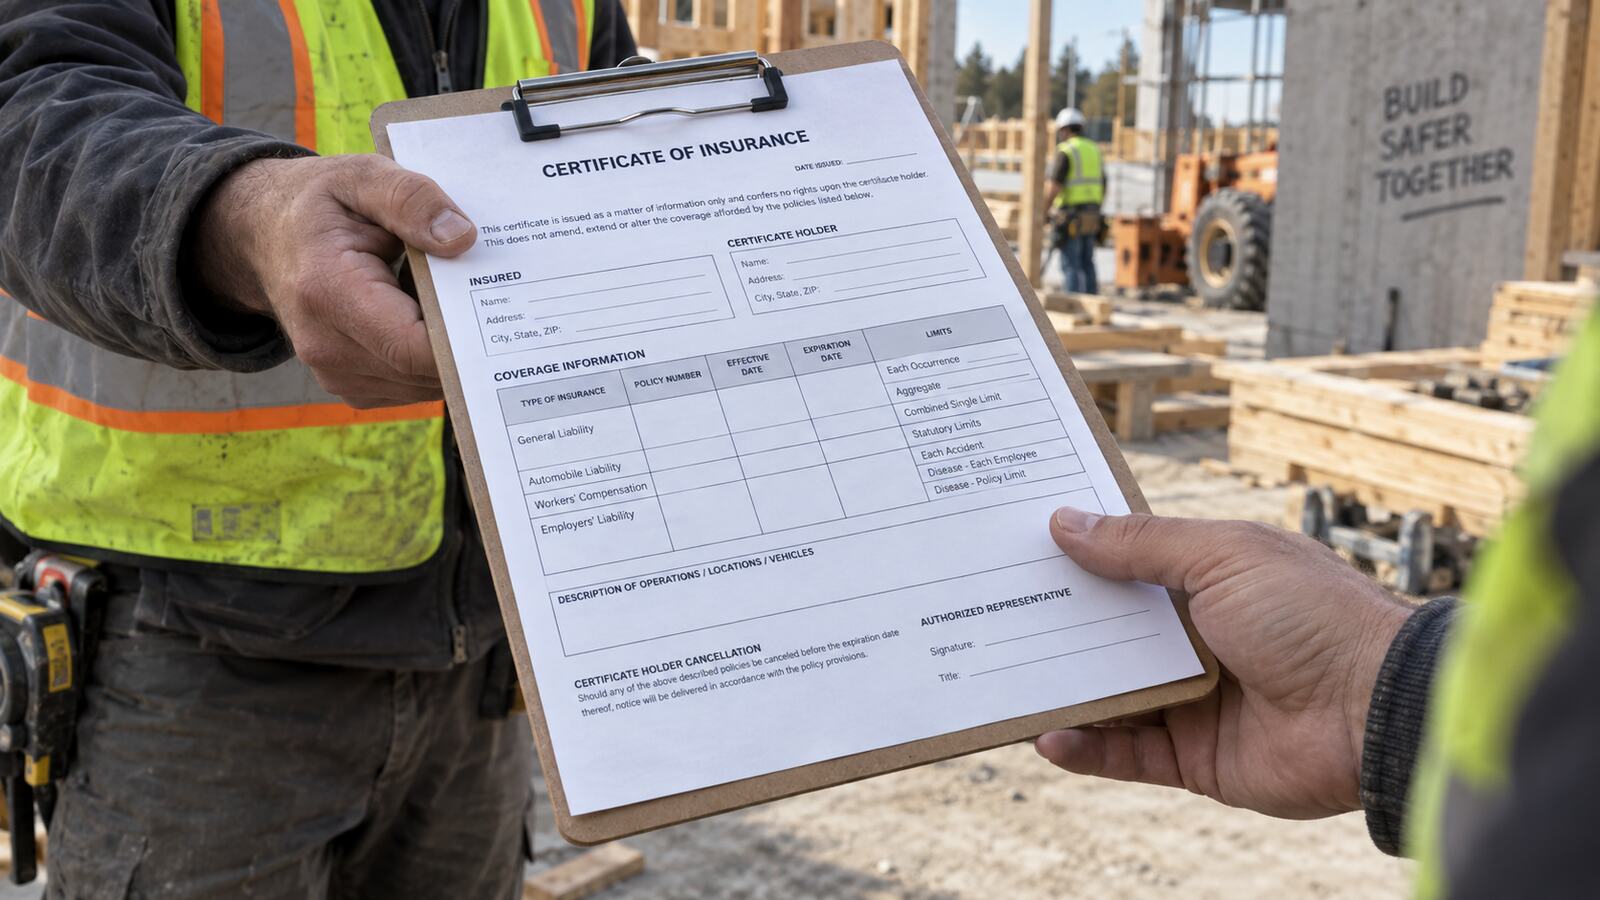
- A certificate of insurance is a one page summary proving coverage exists. It is not the policy and it grants nothing by itself.
- If the add on is not on the policy, the certificate is wrong and the customer is not really covered.
- Get the contract language to your agent during the bid. After you sign, you owe it whether or not you can afford it.
A certificate of insurance is a one page summary proving coverage exists. When a customer asks for one, they usually want something more. They want to be named on your policy, or they want your insurer to give up a right. It is not the policy and it grants nothing by itself. What matters is the endorsements behind the words on it, the add ons written into the policy.
The three requests you will see
- Additional insured. This extends your liability coverage to the customer for claims that come out of your work. It is a real add on with a real cost. It must be written into the policy, not just typed on the certificate
- Waiver of subrogation. Your insurer gives up the right to collect from the customer, even if the customer caused the loss. Common in construction contracts, and usually available for a modest charge
- Primary and noncontributory. Your policy pays first, and the customer's policy does not chip in until yours is used up
Read the contract before you sign
The insurance section of a contract is where the cost hides. Say it demands five million dollars of auto liability, a waiver, additional insured status on a primary basis, and thirty days notice of cancellation. That is asking for real money. Get the language to your agent during the bid. After signing, you owe it whether or not you can afford it. Contractors see the steepest requirements. See what general contractors ask for.
Notice of cancellation
Many contracts say the insurer must warn the customer 30 days before it cancels. Most carriers will not agree to that. Certificates now carry standard wording about it. If the customer insists, the fix is usually a negotiation rather than an endorsement.
What a certificate cannot do
- It cannot add coverage the policy does not have
- It cannot change policy terms, no matter what is typed in the description box
- It does not prove the policy is still in force today, only on the day it was issued
Practical habits
- Keep a current certificate on file for every subcontractor you hire. Check the end dates
- Ask anyone who works for you for a certificate that names your business as additional insured. See why non owned auto matters when subcontractors drive.
- Send regular customers a new certificate at renewal, before they ask
- Save a copy of every certificate you issue, so you know what you promised
We issue same day
Send the requirements and the customer's exact legal name and address, and we will get the certificate out, usually within the hour. Food trucks and event vendors need them constantly. See food truck insurance in Texas. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Does adding an additional insured raise my rate?
Usually a small charge. Some policies include blanket additional insured status when a written contract requires it. That is the least expensive way to satisfy it.
Can I just type the wording on the certificate?
No. If the add on is not on the policy, the certificate is wrong and the customer is not really covered. That is a serious problem for both sides.
What is a blanket endorsement?
One add on that covers anyone you have agreed in writing to include, as additional insured or with a waiver. It saves paperwork when you issue many certificates.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.