
Radius of operation and why it changes your premium
Local, intermediate and long haul rating, what happens when you take one load out of state, and how to keep the classification honest.
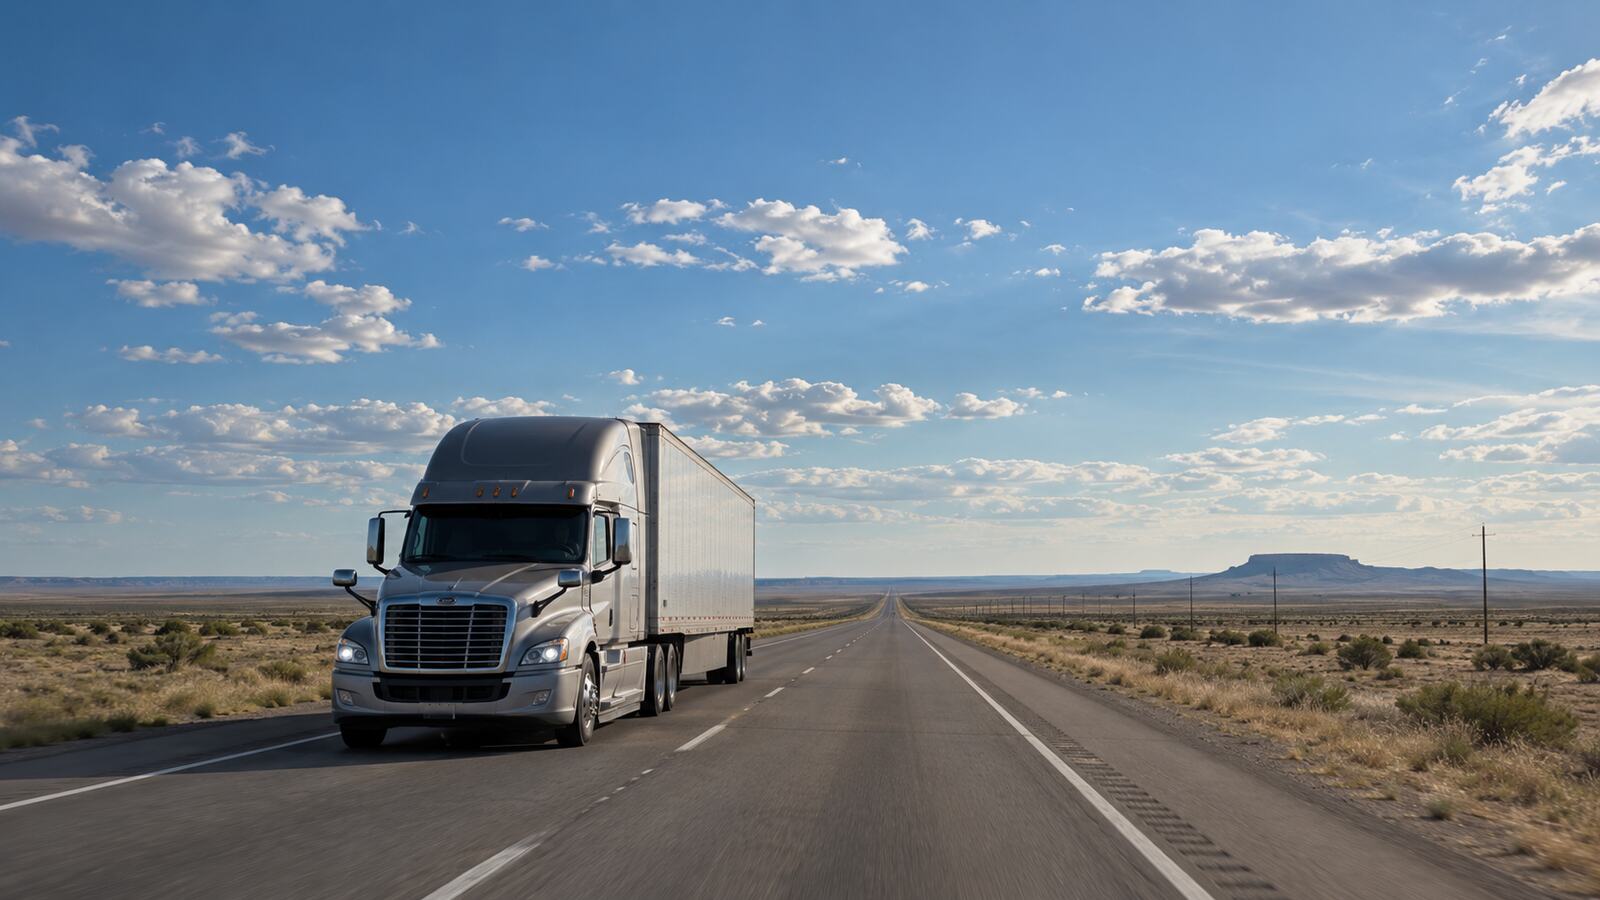
- The further your trucks go from where they are parked, the higher the rate, because highway miles produce worse accidents than city miles.
- If your policy is rated local and you take a load to Dallas, you have operated outside the classification.
- If your operation tightened, say so and get reclassified. We have seen renewals drop meaningfully on nothing more than an accurate radius.
Radius of operation is how far your trucks travel from where they are parked. The further they go, the more the policy costs. It is one of the largest rating factors in commercial auto, and one of the easiest to get wrong on an application.
The radius bands carriers use
- Local, generally within 50 miles
- Intermediate, roughly 51 to 200 miles
- Long haul, beyond 200 miles
Carriers define these a little differently, and some use a fourth band for statewide or nationwide. The further you go, the higher the rate, because highway miles produce worse accidents than city miles.
How the number is measured
It is a radius, not total miles driven. A truck that runs 300 miles a day inside a 40 mile circle around McAllen is still local. A truck that makes one run to Houston is not.
The occasional long trip
This is where operators get into trouble. If your policy is rated local and you take a load to Dallas, you have operated outside the classification. Some policies limit coverage in plain words. Others do not. Either way, at renewal the carrier can reclassify you and charge more after looking at your records. A serious accident on that trip is where it becomes a real problem.
The fix is simple. Tell your agent. Paying to rate the occasional trip costs far less than the fight over whether it was covered. If you are rated local and thinking about a Dallas lane, see how long haul changes a box truck policy.
Keeping it honest works in your favor too
Businesses that cut back a route often keep paying long haul rates for years. If your operation tightened, say so and get reclassified. We have seen renewals drop meaningfully on nothing more than an accurate radius.
What underwriters will check
- ELD and GPS records. An ELD is the electronic logging device that records a truck's hours and location
- Fuel receipts and IFTA filings, the fuel tax reports that show which states you ran in
- Bills of lading and rate confirmations
- Your website and load board activity
Related classifications that matter
Along with radius, carriers rate what you haul, the weight class of the truck, and whether you run under your own authority or lease onto someone else's. All four should match reality on the application. See the other factors that set the price and what operating under your own authority involves.
Get it right at renewal
We will map your real lanes against your policy classification. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
What if my radius changes mid year?
Call your agent and endorse the policy, meaning change it in writing. The premium adjusts, and the coverage matches what you are doing.
Does a rare out of state trip really matter?
One trip rarely reclassifies your whole operation, but it should be disclosed. Regular trips definitely do.
Is radius measured by road miles or straight line?
Most carriers use air miles, a straight line from where the truck is parked. Ask yours, because the difference matters near a band boundary.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.