
Deductibles, downtime and getting a truck back on the road
Rental reimbursement, loss of use, and the coverages that decide how long a damaged truck stops your income.
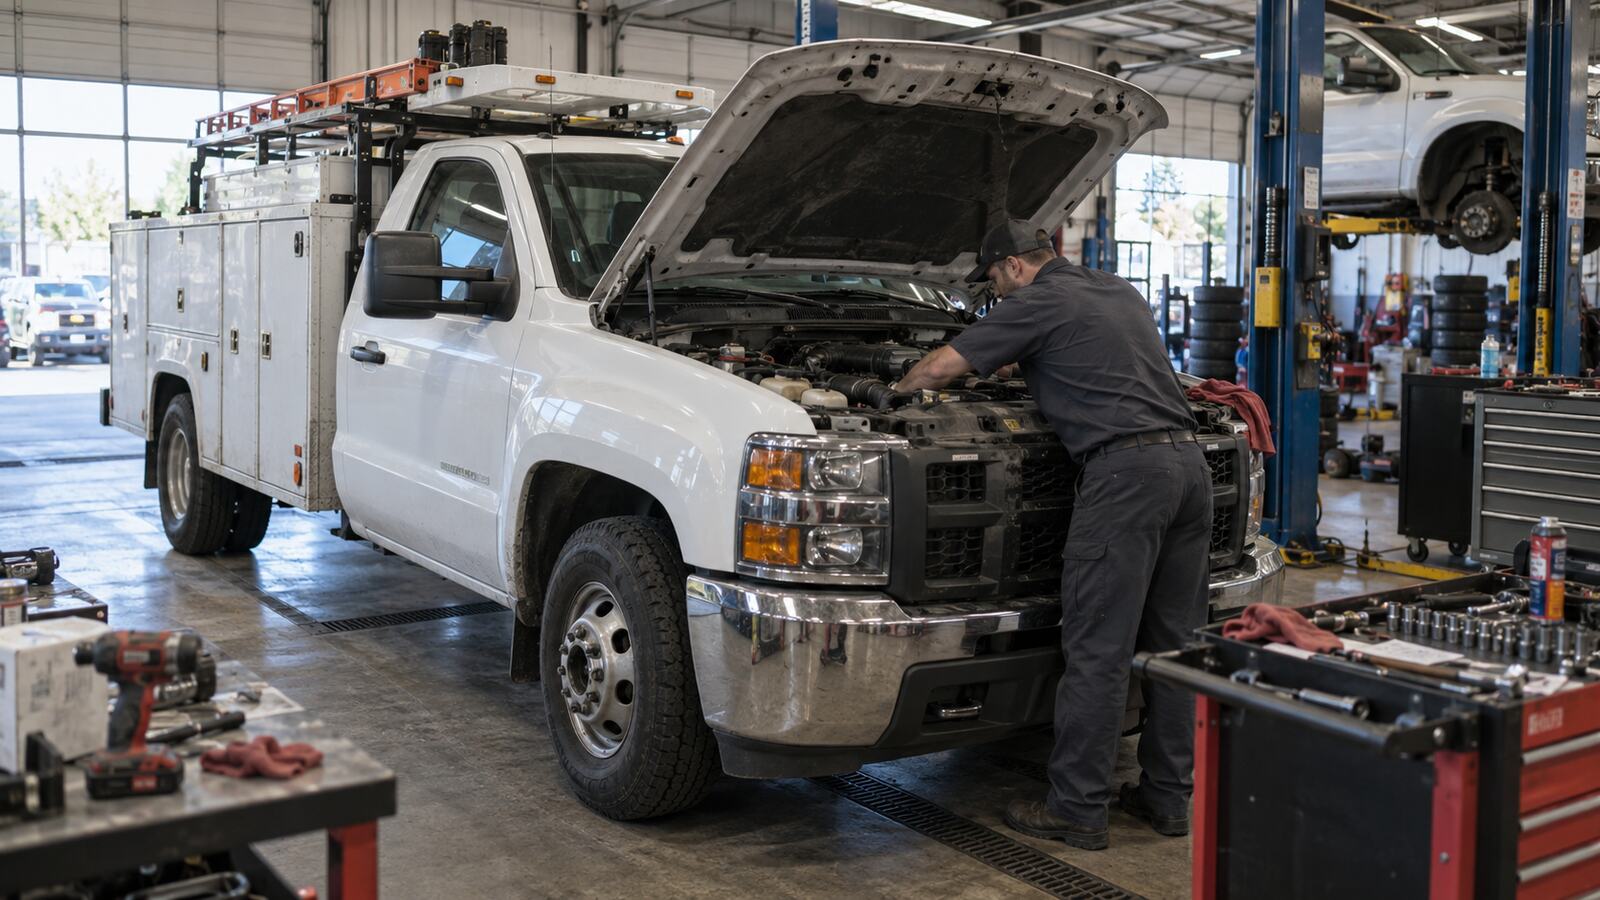
- A truck in the shop for three weeks is three weeks of income that does not arrive, and standard policies do very little about that unless you asked.
- Check the daily rental limit against what a comparable truck really rents for locally. A 100 dollar daily limit does not rent a box truck.
- Tell us how many days off the road would really hurt and we will build the coverage to that.
For a business with one or two trucks, the repair bill is not the biggest cost of an accident. The downtime is. A truck in the shop for three weeks is three weeks of income that does not arrive. Standard policies do very little about that unless you asked for it.
Choosing a physical damage deductible
The deductible is the part of a repair you pay yourself before the policy pays. The logic is the same as personal auto, applied to a business. A higher deductible lowers the premium, and the question is whether the business can absorb the loss without stopping work. Many businesses take 1,000 dollars on newer trucks and 2,500 on older ones. See where deductibles sit among the other cost factors.
The coverages that address downtime
- Rental reimbursement for commercial vehicles, which pays for a substitute truck while yours is repaired, up to a daily limit and a maximum
- Loss of use or downtime coverage, which pays a daily amount when no substitute is available. Common on tractor and trailer policies
- Towing and roadside assistance, which matters more on a heavy truck than most people budget for
Check the daily limit against what a comparable truck really rents for locally. A 100 dollar daily limit does not rent a box truck.
Getting the repair moving
- Report the claim the same day, because heavy truck parts and body shop scheduling take the longest
- Take photographs before the truck is towed
- Send the adjuster your registration, the driver information and the police report in one package, not in pieces
- Ask about a direct repair shop if speed matters more than choosing your own shop
- Keep every receipt for towing, storage and the substitute truck
Total loss on a work truck
Actual cash value is what the truck was worth the moment before the loss. On a work truck it should include the upfit: the bed, the lift gate, the shelving, the wrap. If those were not disclosed when the policy was written, they may not be in the valuation. Give your agent the build sheet and get the value stated correctly before you need it. Food trucks and upfitted service trucks are the usual victims. See valuing a food truck build out.
Plan for the gap
Even with rental coverage there is usually a gap of a few days at the front of a claim. Businesses that keep a relationship with a local rental yard get back to work faster than those making the first call after the accident. At fleet size the math changes. See when a fleet policy makes sense.
We will structure it around your operation
Tell us how many days off the road would really hurt and we will build the coverage to that. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Is rental reimbursement worth it on a commercial policy?
For a one or two truck operation, usually yes. For a fleet with spare trucks, often not.
Does the policy pay lost income?
Auto policies generally do not. Business interruption is a property coverage. Downtime endorsements pay a fixed daily amount rather than your actual profit.
Can I choose my own repair shop?
Yes, in Texas. The insurer may recommend one, and cannot require it.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.