
What drives the cost of commercial auto insurance?
Radius, drivers, truck class, cargo and loss history, and which of them you can actually change this year.
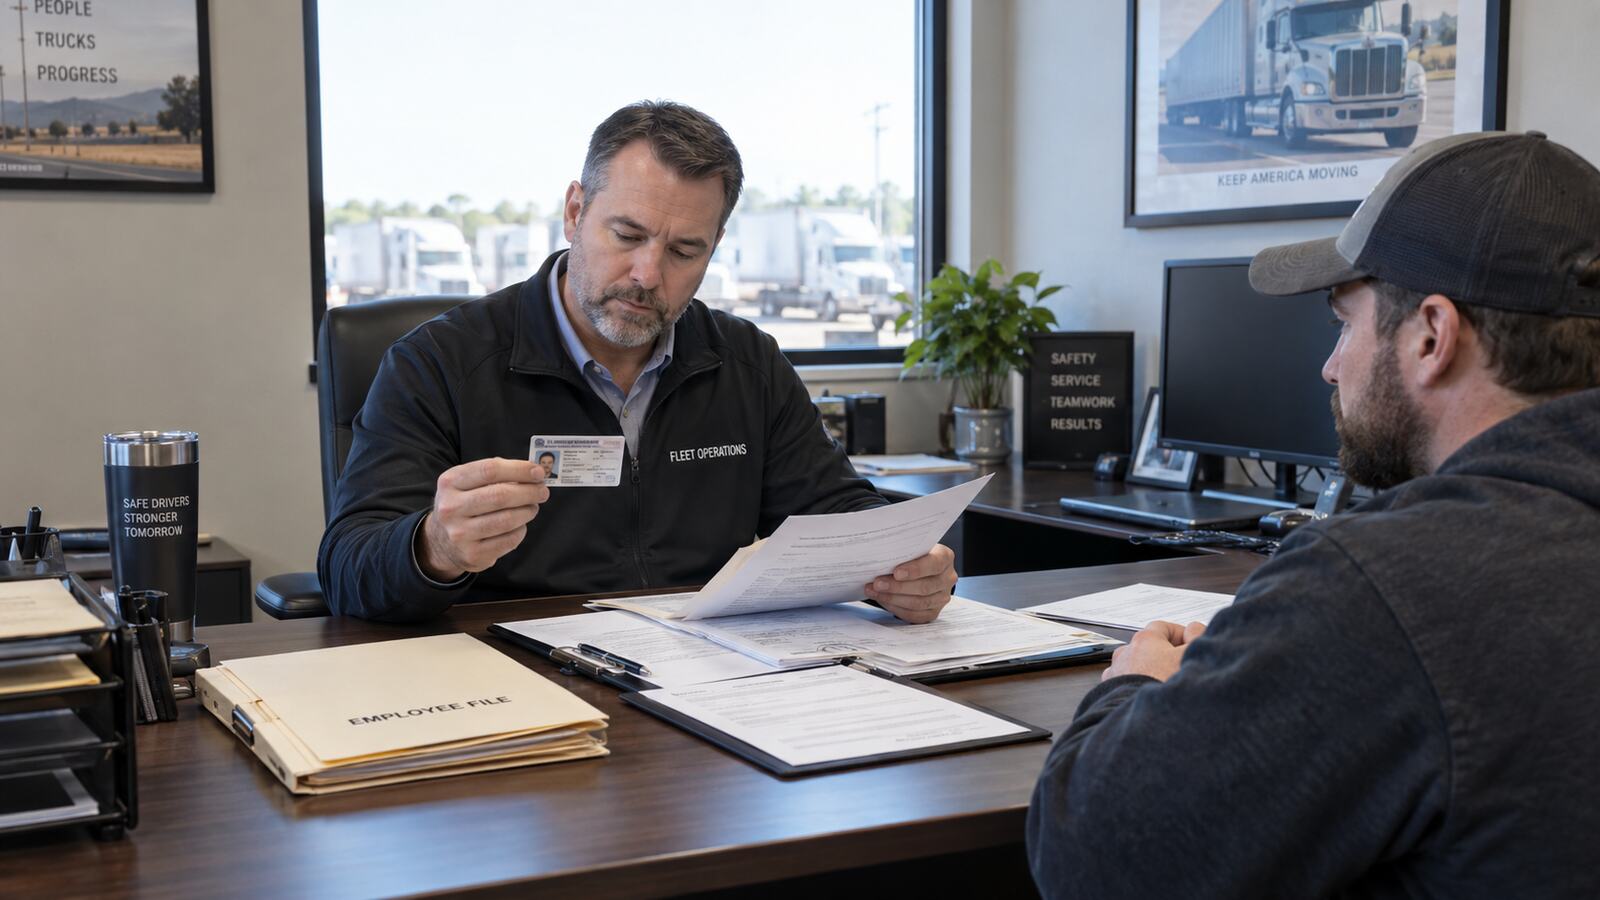
- Driver records are the factor that most often decides whether a policy is quoted at all.
- A new authority with no history pays the most. The second and third renewals are where that corrects, as long as nothing goes wrong in between.
- Pull the driving record on every driver and remove or retrain the outliers before renewal.
Commercial auto premiums vary far more than personal ones. The premium is the bill you pay for the policy. The underwriter, the person at the company who prices the risk, is rating a business rather than a person. The factors that move it most are radius, driver records, truck type, what you haul and your loss history. Knowing which ones carry weight tells you where to spend effort.
The factors that move commercial auto rates most
- Radius of operation, how far your trucks travel from where they are parked. Local, intermediate and long haul are priced very differently. Moving from a 100 mile radius to nationwide changes the number a lot. See how radius is measured and rated.
- Driver records. This is the factor that most often decides whether a policy is quoted at all. See managing the driver list.
- Truck weight class and type. A one ton pickup, a box truck and a tractor are three different products
- What you haul, and for whom
- Years in business and years under your DOT authority
- Loss history, your record of past claims, usually looked at over three to five years
- Your liability limit, and whether an umbrella, an extra layer of liability, sits above it
What you can change quickly
- Pull the driving record on every driver and remove or retrain the outliers before renewal
- Put your hiring standards in writing, because underwriters ask about them
- Raise physical damage deductibles, the part of a truck repair you pay yourself. That lowers the premium without touching liability. See choosing a deductible without stalling the business.
- Install telematics or dash cameras. Telematics are devices that record how a truck is driven. Several carriers give credit for them. They also win disputed claims
- Keep the truck list accurate. Businesses routinely pay for trucks they sold
What takes longer
Loss history and years in operation. Both improve on their own if you keep claims down. A new authority with no history pays the most. The second and third renewals are where that corrects, as long as nothing goes wrong in between.
Where businesses waste money
- Buying only the minimum limit and then paying for an expensive umbrella to sit above it
- Carrying physical damage on a paid off truck worth less than a few thousand dollars
- Not reporting a smaller radius after the operation changed
- Renewing without shopping. The commercial market moves in cycles, and carriers enter and leave segments all the time
Safety programs pay for themselves
Underwriters ask about a written safety program, driver training records, a maintenance file and a phone use policy. All of them move pricing. They also cut the claims that raise your rate in the first place. At five or more trucks this becomes fleet pricing, where your own loss history drives the number.
We will benchmark your renewal
Send us your declarations page, the summary page of your policy, and your loss runs, the report of your claims. We will tell you whether the renewal is fair. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Why did my premium jump without any claims?
Commercial auto rates have gone up across the whole industry, driven by repair costs and lawsuits. Shop it every year rather than assuming the increase is about you.
Do loss runs matter that much?
Yes. Underwriters price on your five year history. Clean loss runs are the strongest argument you have at renewal.
Does adding a young driver change the price?
On commercial policies, driver age matters less than record and experience. An inexperienced driver on a large truck still moves the number, and can affect whether the company will write the policy at all.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.