
Motor truck cargo insurance for produce haulers
Reefer breakdown, rejected loads, and the exclusions that decide whether a spoiled trailer of produce gets paid.
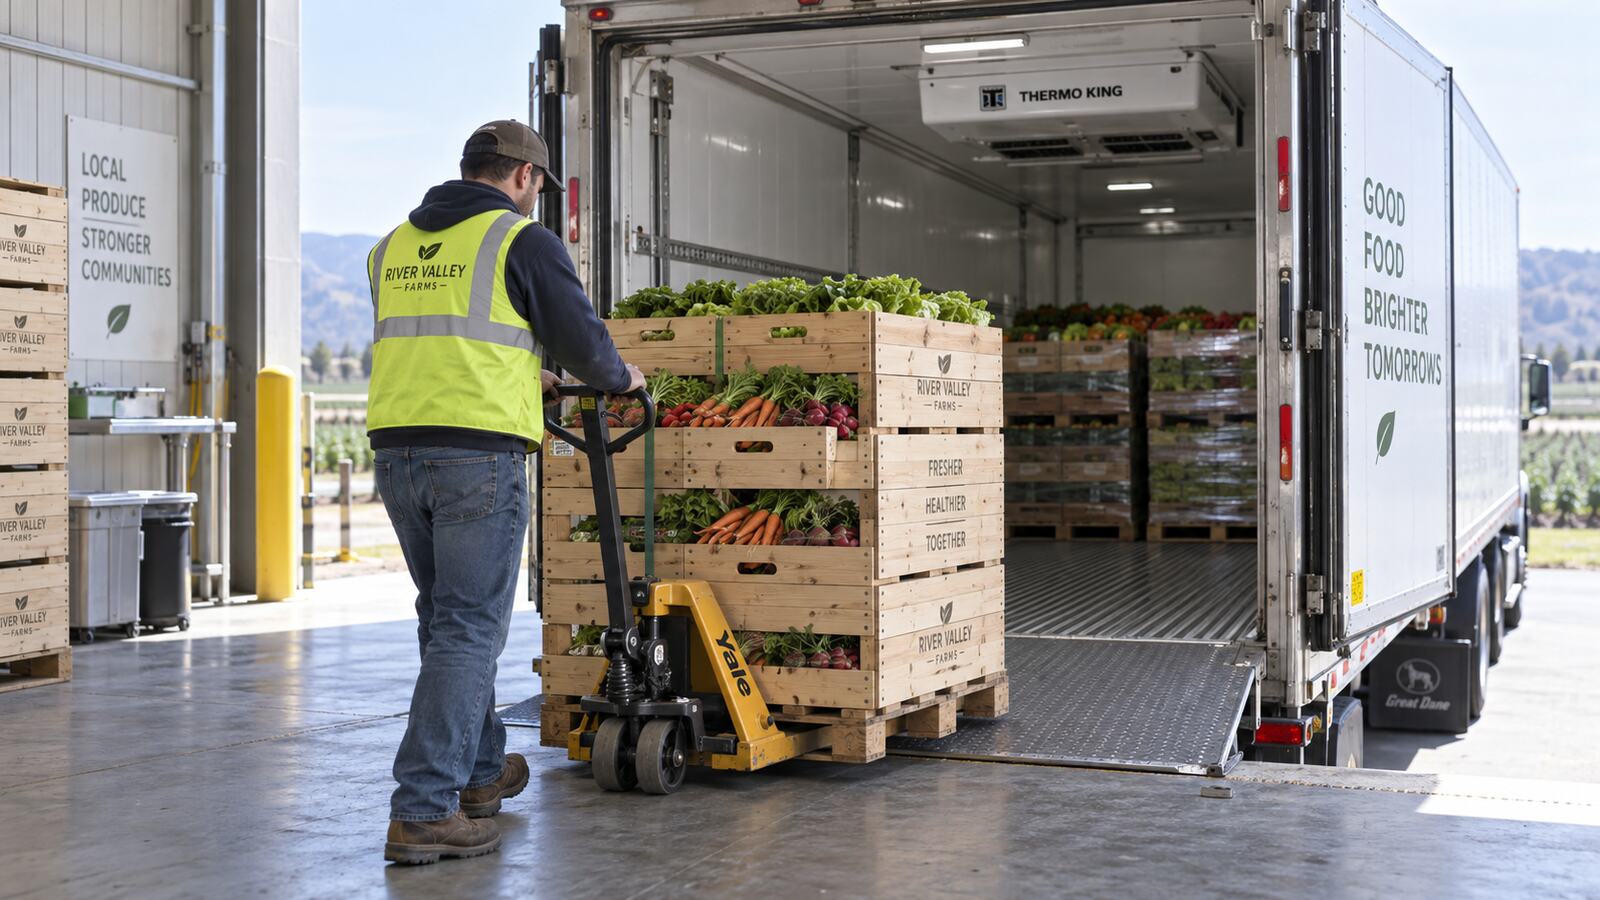
- Motor truck cargo covers damage to or loss of the freight you haul, up to the policy limit, while it is in your care.
- A standard cargo policy does not pay when the refrigeration unit fails. You need the reefer breakdown endorsement, and it comes with conditions.
- Set the limit to the highest value load you actually haul, not the average. Receivers and brokers often require 100,000 dollars, and more for some loads.
Motor truck cargo insurance pays for damage to or loss of the freight you haul, up to the policy limit. For produce, the part that matters most is the reefer breakdown endorsement. A standard cargo policy does not pay when the cooling unit fails. Produce moves through South Texas year round, and cargo claims on cold loads follow a pattern. Most denials trace back to two or three lines in the policy that nobody read until the load was turned away.
What motor truck cargo covers
Damage to or loss of the freight you haul, up to the policy limit, while it is in your care, custody and control. That means from pickup until you hand it over. It is separate from liability, which covers harm to others. It is also separate from physical damage, which covers your truck. See coverage for a trailer you do not own.
The reefer breakdown exclusion
Standard cargo policies exclude loss caused by a cooling failure unless you buy the reefer breakdown endorsement, an add on to the policy. Say you haul cold freight without it. A compressor fails and spoils 40,000 dollars of produce. That is your loss, not the insurer's.
The endorsement usually comes with conditions. Documented maintenance on the unit. A temperature recorder that runs the whole trip. A set point, the temperature the load must be kept at, written on the bill of lading. Miss those and the endorsement can still fail you.
Other exclusions worth reading
- Improper packing or loading by you
- Failing to keep the required temperature, which is different from a breakdown
- Theft from a truck left alone, which many policies limit to watched or locked locations
- A late delivery, which is almost always excluded even when it causes the loss
- Commodities not listed on the policy
How to protect a claim before it happens
- Cool the trailer to the set point before loading and record it
- Photograph the load, the seal and the temperature display at pickup
- Get the set point in writing on the bill of lading, not by phone
- Keep the download from the temperature recorder for every load
- Note any existing pallet damage on the bill of lading at pickup, in the driver's handwriting
- Service the reefer on schedule and keep the receipts
Limits and deductibles
Set the limit to the highest value load you actually haul, not the average. Receivers and brokers often require 100,000 dollars, and more for certain loads. The deductible is the part of a loss you pay yourself. Cargo deductibles run higher than auto deductibles, often 1,000 to 5,000 dollars. See how deductibles work on a work truck.
We know these accounts
Bring a recent rate confirmation and a bill of lading. We will match the coverage to what you actually haul. Starting out? See the insurance checklist for a new trucking business. Use the commercial quote form on this page, or call our McAllen office at (956) 687 3334. Se habla español.
Common follow-up questions
Is cargo insurance required?
Brokers and shippers require it by contract, commonly at 100,000 dollars. Household goods movers have a federal filing rule. For most other freight it is the contract that requires it, not the law. Texas movers that stay inside the state must also file cargo coverage with TxDMV. That is at least 5,000 dollars for one shipper's cargo on a truck, and 10,000 dollars for several shippers, under 43 Texas Administrative Code 218.16.
Does cargo coverage pay the full invoice value?
It pays up to your limit, minus the deductible, and by how the policy values the freight. Read the valuation clause. Some pay wholesale value rather than invoice.
What if the receiver rejects a load that is not actually spoiled?
That is a common dispute. Temperature records and photos are what settle it. That is why the paperwork habits matter more than the policy language.
Commercial auto quote. Eight quick questions, then a licensed agent in McAllen calls you with the number.
What do you drive for work?
Pick the closest one. Your agent will sort out the details.
How many trucks?
Count every vehicle the business uses, including one you own personally.
What is the work?
Welder, landscaper, produce hauling, deliveries. A few words is enough.
Does a customer or general contractor need a certificate from you?
Many contracts ask for a one million dollar limit. If you have the requirement in writing, keep it handy for the call.
Do you have a USDOT number?
Needed for crossing state lines in a truck over 10,000 pounds. Not sure is a fine answer.
Who are we quoting?
So your agent knows who they are calling.
Where should we call you?
One call with your quote. No robocalls, no list selling.
Want a copy by email?
Optional. It means you have the numbers in writing after the call.
By pressing “Get my quote” you agree a licensed McAllen Insurance Group agent may contact you by phone, text or email at the details you provide, including by automated dialing. Consent is not required to buy. This is a request for a quote, not an application, and not an offer of coverage.
Getting your request to an agent
We have your request
An agent will call you with the quote. Have your registration and any contract requirements nearby. If you would rather not wait, call us now.
Call (956) 687 3334Monday to Friday, 9 AM to 6 PM. Se habla español.
Read next
Do I need commercial auto insurance?
Commercial Auto · 4 min read

Gerino Alejos
Licensed insurance agent · License 3128710 · NPN 18243381
Owner of McAllen Insurance Group, an independent agency on North 10th Street in McAllen. Works with clients across Hidalgo, Cameron and Starr counties on Medicare, Marketplace health, life and auto coverage. Se habla español.